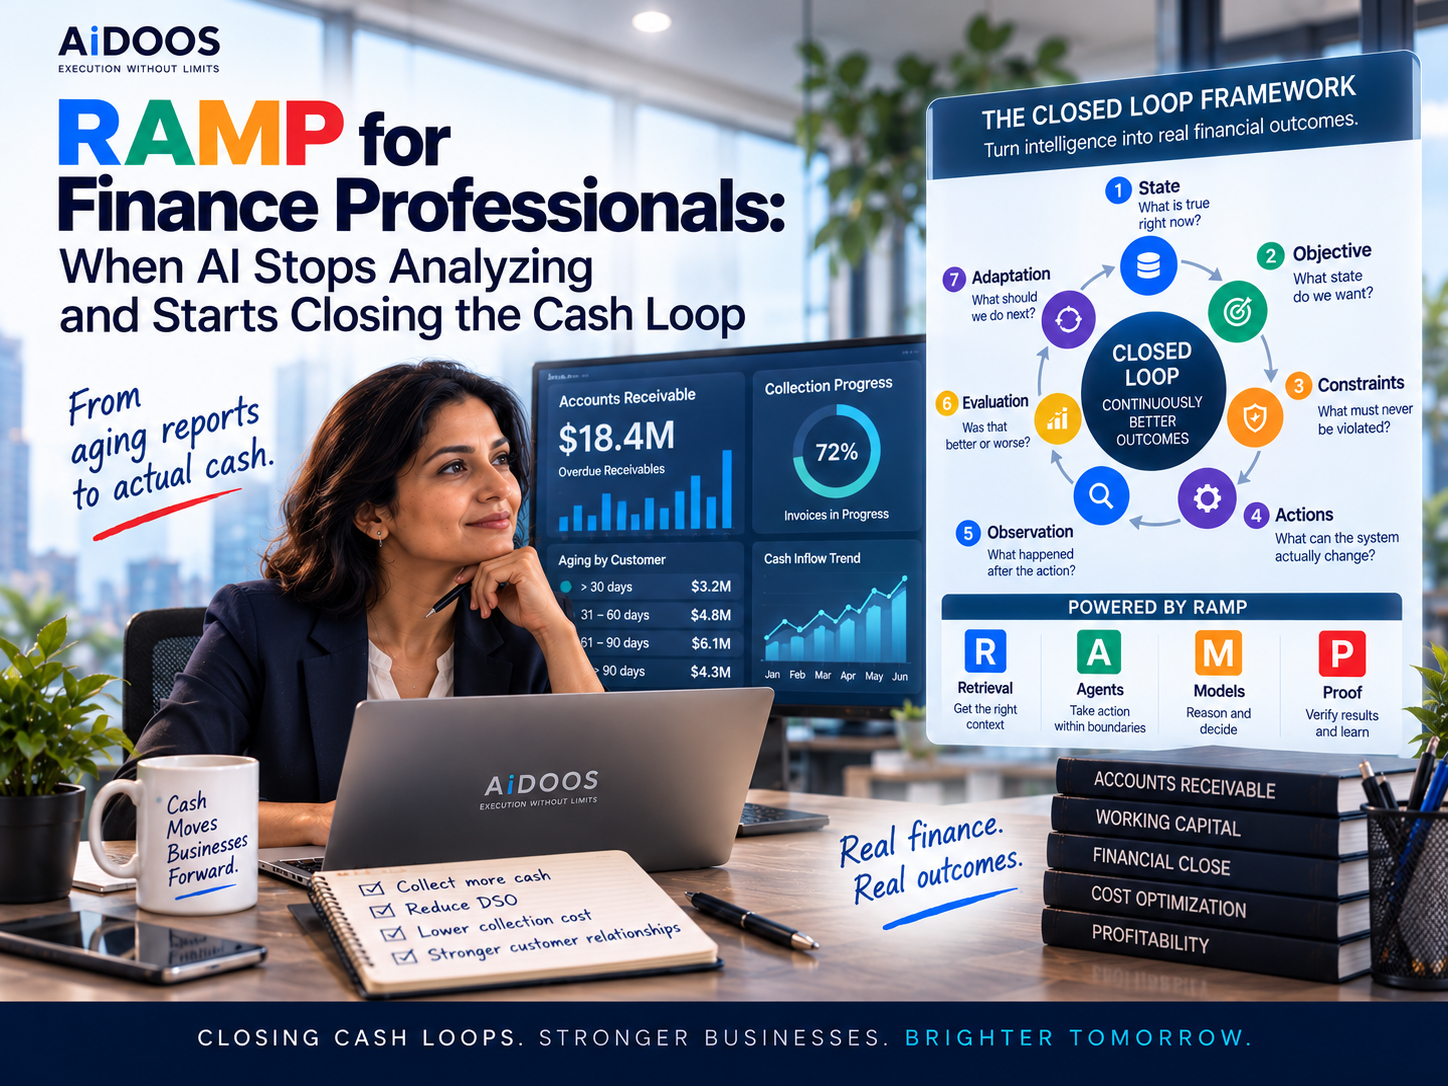
RAMP for Finance Professionals: When AI Stops Analyzing and Starts Closing the Cash Loop
Anita is looking at the same number she looked at last Monday.
$18.4 million.
That is the amount sitting in accounts receivable beyond the company's preferred collection window.
The number appears on a beautifully designed dashboard. It is broken down by geography, customer, invoice age, salesperson, payment terms, and risk category.
There are charts showing the movement over the last twelve months. There is a heat map showing where the problem is concentrated, and there is even an AI-generated summary explaining that overdue receivables have increased primarily among a handful of large enterprise accounts.
The analysis is good.
The cash is still not in the bank.
Anita is the company's finance operations leader, and she has spent years improving visibility into working capital. Her team knows which customers owe money, how late they are, what was promised, and which invoices are disputed.
Yet almost every Monday begins the same way.
Someone exports the aging report. Someone assigns accounts. Someone checks CRM notes. Someone emails sales. Someone contacts the customer.
Then everybody waits.
A customer responds.
Or does not.
A promise-to-pay date is recorded.
The date passes.
Someone notices later and starts another round of follow-up.
Anita begins to wonder whether the company's collections problem is really an information problem.
Perhaps the dashboard already knows enough.
The missing piece is what happens after the dashboard.
That distinction is where RAMP and Closed Loops become particularly interesting for finance professionals.
The opportunity is not merely to use AI to understand the number faster.
It is to build a system that keeps working on the number until the business outcome changes.
1. Finance has spent decades becoming better at seeing the business
Modern finance organizations are surrounded by information.
Revenue is visible.
Margins are visible.
Cash positions, overdue invoices, expense movements, forecast variance, utilization, payment cycles, vendor spend, and working capital can all be examined with enormous precision.
Compared with previous generations, today's finance leader can see the organization remarkably well.
Yet seeing and changing are different capabilities.
Anita's aging report is a perfect example.
The company knows that a customer owes $420,000.
It knows that two invoices are forty-seven days overdue. It knows the customer disputed one line item, the sales account owner promised to resolve it, and the customer subsequently said payment would be processed after the correction.
All of that information is visible somewhere.
Still, somebody has to move the issue forward.
The collections analyst checks whether the credit note was created. The analyst contacts sales, then waits for a response.
Once the issue is corrected, somebody tells the customer. A few days later, somebody checks whether payment was received.
If it was not, the process begins another lap.
This is a recurring pattern across finance.
The organization has increasingly automated visibility, while humans still carry much of the movement between observation and outcome.
AI can make the reports smarter.
A model can explain why DSO increased or identify which customers are likely to pay late.
Those capabilities are useful, but they do not by themselves change the cash position.
The finance professional of the AI era therefore needs to start asking a different question.
Not only, “What does the data tell us?”
But, “What should happen next, and can the system keep pursuing the outcome?”
That is the beginning of a Closed Loop.
2. RAMP changes when finance points it at a number someone owns
Anita chooses collections as the first problem because the desired outcome is unusually concrete.
The company does not want better insight into overdue invoices.
It wants cash.
That clarity is useful because it forces the team to define what the loop is actually trying to accomplish.
The Retrieval layer comes first.
To understand an overdue invoice, the system may need much more than the aging table.
It needs the invoice itself, contractual payment terms, customer history, previous collections activity, disputes, credit notes, account ownership, communication history, payment promises, current account health, and perhaps information about open service issues.
This is where finance teams often discover that the collection process crosses organizational boundaries.
The finance system knows an invoice is overdue.
The CRM knows the customer is negotiating a renewal.
Support knows there is an unresolved issue.
Sales knows the CFO personally promised the customer that a commercial dispute would be resolved before payment.
No single system contains the whole truth.
A collections analyst traditionally reconstructs this context manually.
RAMP changes that.
Retrieval can assemble the relevant state around the invoice before the analyst, agent, or model decides what should happen next.
That immediately improves the quality of action.
A customer who simply forgot to process an invoice should not receive the same treatment as one withholding payment because of a legitimate dispute.
A strategic customer nearing renewal should not necessarily receive the same automated escalation as a small account that has ignored six reminders.
The amount may be identical.
The context is not.
This is why a good Closed Loop cannot begin with “send an email after 30 days.”
That is automation.
A loop begins by understanding the state well enough to choose an appropriate action.
3. The collections agent should not become the world's most persistent spammer
Once Anita's team can retrieve the right context, the next temptation is obvious.
Automate the follow-up.
An agent can draft emails, send reminders, monitor responses, update the finance system, and schedule the next action without requiring a collections analyst to touch every invoice.
The productivity potential is enormous.
It is also very easy to get wrong.
Imagine a customer with five overdue invoices.
The company is waiting for a promised credit adjustment. Sales is in the middle of a major expansion discussion, and the customer's finance team has already explained that all five invoices will be processed together once the correction arrives.
A naive collections agent sees five overdue invoices.
It sends five reminders.
Then another set three days later.
Technically, the automation worked.
Commercially, it made the company look disorganized.
This is where Agents in RAMP become an authority-design problem rather than merely an automation tool.
The agent needs an action space.
Perhaps it can send routine reminders automatically when there are no disputes, no active promises, and no strategic account conditions requiring human review.
It can request information from an internal owner.
It can generate a payment link, prepare a statement, ask for a promise-to-pay date, or follow up when that date passes.
Other actions may require judgment.
Should the account be placed on credit hold?
Should a sales leader intervene?
Should the customer receive a payment plan?
Should late fees be waived?
Should a legal process begin?
An agent may help assemble the evidence for these decisions.
It should not necessarily make all of them autonomously.
The RAMP-ready finance professional therefore does not ask, “How do we automate collections?”
They design a ladder of authority.
Routine, reversible actions can happen automatically.
Commercially sensitive or high-consequence decisions move toward human judgment.
This is what humans by exception actually means in a finance context.
It does not mean humans disappear.
It means expensive human attention is reserved for situations where it changes the outcome.
4. Models can predict payment, but prediction is not the business objective
Anita's team adds another capability.
A model predicts the probability that each customer will pay within the next two weeks.
The early results look impressive.
Some customers historically pay five or ten days late regardless of reminders. Others respond immediately when contacted.
Certain dispute types correlate strongly with long delays.
The model can help prioritize effort.
But Anita notices something important.
The highest-risk customer is not necessarily the customer that deserves the strongest intervention.
Suppose Customer A owes $50,000 and has a low probability of paying this month.
Customer B owes $3 million and has a moderately high probability of paying.
The company's decision cannot be based only on payment probability.
The size of the exposure matters.
So does strategic importance, dispute status, available actions, customer relationship, and the cost of waiting.
This is the Models capability inside the loop.
Models contribute intelligence.
They do not define the business objective.
A forecast can estimate what may happen.
A reasoning model can evaluate the situation.
A classification model can identify likely dispute categories, while another model can summarize the latest customer correspondence.
All of this intelligence can improve the decision.
But the finance organization still needs to define what it is optimizing.
Cash collected?
DSO?
Customer retention?
Collection cost?
Bad-debt risk?
Perhaps several at once.
This is where AI projects often become confused.
A team optimizes a metric because it is measurable rather than because it represents the outcome the business actually cares about.
An agent could aggressively reduce overdue receivables by putting customers on credit hold sooner.
The cash metric might improve.
Revenue could suffer.
The loop needs to understand the tradeoff.
This is why the finance professional remains central.
The machine can reason across numbers.
Someone still needs to understand what the numbers mean to the business.
5. Proof is not “the reminder was sent”; Proof is “the cash moved”
A week later, Anita reviews the first results from the new collections workflow.
The dashboard looks fantastic.
Ninety-four percent of scheduled reminders were sent successfully.
Internal follow-up tasks were created automatically. Customer responses were classified, promises-to-pay were extracted from emails, and CRM notes were updated without manual entry.
The project team is pleased.
Anita asks a less comfortable question.
“How much cash did this change?”
The room gets quieter.
This is the Proof problem.
Organizations frequently confuse successful execution with successful outcomes.
The email was sent.
The task was completed.
The customer was contacted.
The agent performed exactly what it was asked to perform.
None of those facts proves that collections improved.
Anita wants to know whether customers paid sooner.
Did fewer promises-to-pay get missed?
Were disputes resolved faster?
Did the amount moving into older aging buckets decline?
Did collection cost fall without harming important customer relationships?
That is Proof at the business level.
The difference matters because a Closed Loop must observe what happened after the action.
Suppose the agent sends a reminder and the customer replies that an invoice contains an incorrect tax amount.
The loop should not record “customer contacted” and wait seven days.
It should recognize that the state has changed.
The next objective is no longer simply payment follow-up.
The blocker has become dispute resolution.
The loop may retrieve the invoice and contract terms, identify the responsible internal team, request correction, monitor whether the correction happens, send the revised document, and then resume the payment cycle.
That is what closing the loop means.
The system does not blindly repeat the same action.
It responds to what happened.
This is also where many workflows that look “agentic” are still fundamentally open.
An agent executes a sophisticated task.
Then a human has to notice the result and decide what happens next.
The agent acted.
The loop did not close.
6. Collections becomes a seven-step business loop
Anita's team eventually puts the seven-step Closed Loop framework on the wall beside the collections dashboard.
They use it whenever somebody proposes a new automation.
The first question is State.
What is true now?
For collections, that includes the amount overdue, invoice age, dispute status, customer communications, previous promises, account importance, and any internal blocker affecting payment.
Then comes the Objective.
What state are we trying to reach?
For an individual invoice, the obvious answer is payment, but the business objective may be slightly broader: collect the cash within an acceptable period without unnecessarily damaging the customer relationship or creating disproportionate collection cost.
Next come Constraints.
A strategic account may require account-owner involvement beyond a certain escalation level. Legal notices cannot be issued casually, and customer commitments already made by sales or finance need to be respected.
The loop then identifies available Actions.
Send a reminder.
Request supporting information.
Resolve a dispute.
Escalate internally.
Ask for a payment commitment.
Offer an approved payment arrangement.
Apply a credit hold under defined conditions.
Move the account to a specialist.
Once an action occurs, the loop needs Observation.
Did the customer respond?
Was a promise-to-pay made?
Was the dispute resolved?
Did payment arrive?
Did the customer raise another issue?
Then comes Evaluation.
Did the action move the account closer to the objective?
Perhaps the customer promised payment but failed to pay.
That is different from no response.
The next decision should reflect that new state.
Finally comes Adaptation.
The loop chooses what happens next based on the evidence.
A first missed promise might trigger another automated contact.
Repeated missed commitments might require account-owner intervention.
A newly discovered dispute might route the case away from collections until the underlying issue is fixed.
The sequence is familiar:
State → Objective → Constraints → Actions → Observation → Evaluation → Adaptation
What changes is that finance no longer expects a person to manually carry every invoice through all seven steps.
RAMP supplies the capability inside the loop.
Retrieval establishes context.
Models help interpret and decide.
Agents perform appropriate actions.
Proof establishes what happened and whether the outcome improved.
Then the loop adapts and continues.
The goal is not to eliminate the collections team.
It is to stop spending expensive human judgment on cases that do not require expensive human judgment.
7. Once finance sees one loop, it starts seeing them everywhere
Something interesting happens to Anita after collections.
She begins looking at the rest of finance differently.
The monthly close is a collection of loops.
A reconciliation fails.
The system observes the mismatch, retrieves supporting evidence, identifies possible explanations, resolves what can be resolved, verifies the balance, and escalates the cases that remain ambiguous.
Expense management contains loops.
A transaction arrives.
The system determines whether evidence is complete, checks policy, requests missing information, evaluates the response, and keeps moving until the expense is either approved, corrected, or escalated.
Forecasting contains loops too.
Actual results arrive.
The system compares them with forecast assumptions, identifies meaningful variance, retrieves the drivers, updates what has changed, and feeds the learning into the next forecast.
Working capital is full of loops.
Supplier payment timing, inventory, customer collections, cash forecasting, and financing decisions are all connected states that finance continuously observes and tries to influence.
Even profitability can be viewed this way.
A margin problem is detected.
The organization investigates drivers, changes pricing, sourcing, staffing, mix, or process, observes what happened, and decides whether further intervention is required.
What previously looked like a collection of dashboards and monthly management routines starts to look like a collection of partially closed loops.
This changes the AI conversation inside finance.
Instead of asking, “Where can we use AI in finance?” Anita can ask, “Which financial outcomes are humans repeatedly carrying from observation to action?”
That question is far more concrete.
It also tends to expose where real value exists.
A chatbot that explains the P&L is useful.
A loop that detects margin deterioration, identifies the drivers, triggers appropriate interventions, observes what happened, and continues until the condition improves is operating at an entirely different level.
That is the journey from AI assistance to AI-native finance.
8. The finance professional moves from explaining the number to standing behind the number
For years, finance transformation has promised that finance professionals would spend less time producing reports and more time becoming strategic business partners.
Progress has been uneven.
Many finance teams still spend enormous amounts of energy gathering data, reconciling information, preparing packs, chasing inputs, and explaining what happened last month.
AI can finally remove substantial amounts of that mechanical work.
But that does not automatically make finance strategic.
It simply creates capacity.
What finance does with that capacity is the more important question.
Anita's value is not that she can produce another aging analysis.
The system can do that.
Her value lies in understanding why cash is not moving, which interventions make economic sense, which customer relationships deserve different treatment, and what level of autonomy can safely be given to the loop.
She becomes less of a report owner and more of an outcome owner.
That is a meaningful change.
A RAMP-ready finance professional can retrieve the context surrounding a number rather than simply see the number.
They can design agents that act within financial and commercial boundaries, choose the right intelligence for the problem, and insist on Proof that the intervention actually changed the business outcome.
Closed Loops give those capabilities somewhere to go.
The finance professional is no longer learning AI merely so they can work faster.
They are learning how to redesign financial work so the organization can continuously observe, decide, act, verify, and adapt.
Anita still looks at the $18.4 million number.
But six months later, the dashboard means something different.
It no longer represents a pile of invoices waiting for people to work through them.
Most accounts are already moving through loops that know their state, understand the next permitted action, and continue working until the cash arrives or a genuinely difficult case requires human judgment.
Anita sees fewer items.
But the items she sees matter more.
A strategic customer has disputed a significant amount.
Another account is experiencing financial distress.
A commercial decision is required on whether to accept a payment plan.
Those are finance problems worth putting experienced people around.
Everything else should not need somebody to remember to send another email next Tuesday.
That is the larger promise.
RAMP gives finance professionals a way to operate with intelligence.
Closed Loops allow them to apply that intelligence to numbers the business actually cares about.
And when that happens, finance begins moving beyond explaining what happened.
It starts building systems that continuously help change what happens next.